
BY NKECHI NAECHE-ESEZOBOR—If you hold an insurance policy in Nigeria, or have been thinking about buying one, there is one question that comes to your mind. What changes when you make a claim?
That is the test the industry now faces after its successful recapitalisation, the process in which insurers were required to raise their minimum capital. The more of it a company has, the better placed it is to pay when claims arise.
Under the Nigerian Insurance Industry Reform Act (NIIRA) 2025, insurers had to meet new minimum capital levels. The deadline passed on July 31, 2026. The National Insurance Commission (NAICOM), the industry apex regulator, says 48 insurance companies and two reinsurers met the requirement, while six insurance licences were cancelled because those operators fell short. About N1.079 trillion was mobilised, made up of fresh capital and existing funds.
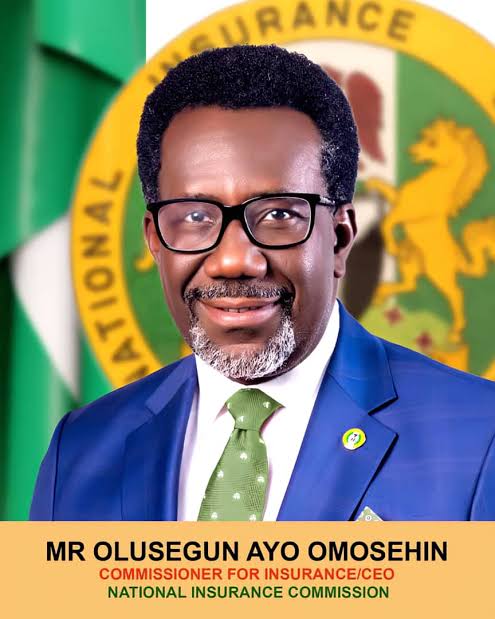
Commissioner for Insurance and Chief Executive Officer, Olusegun Ayo Omosehin, has repeatedly said recapitalisation was not meant to be a destination. The added capital, he argues, should help insurers take on bigger and more complex risks, innovate, improve customer experience and retain more risks in Nigeria.
He has also named claims payment as among the clearest indicators of insurance’s value to policyholders.
This matters because the sector still grapples with low trust, limited awareness, affordability pressures and thin distribution, with penetration below one per cent. Concerns persist about how quickly claims are settled, and for most people a policy proves its worth at the moment of loss.
Recently, the Chairman of Nigerian Insurers Association (NIA), Mrs. Ebelechukwu Nwachukwu, described recapitalisation as a foundation for stronger players able to underwrite large risks, mobilise long-term capital and invest in digital transformation.
She warned operators against treating recapitalisation as the end of the reform process.
“The capital is in place. The legal framework is in place. The question before every boardroom now is what do we do with it?” she asked.
According to her, the real test of the recapitalisation would be whether stronger balance sheets translate into the ability to underwrite larger and more complex risks within Nigeria, improve claims settlement and customer service, and extend insurance coverage to millions of underserved Nigerians.
“Capital is not the destination. It is the foundation. The real question before us is whether the public will see the difference,” she said.
The group Managing Director of AIICO Insurance Plc, Babatunde Fajemirokun, said: “If you look at NIIRA itself, the strong provisions around policy protection and consumer protection, as well as the reasons insurance companies could have used in the past to reject a claim, have been significantly diminished. So, going forward, you would find that insurance companies are more willing to settle claims.
“It might mean underwriting becomes a lot more rigorous, because you shouldn’t underwrite a business if you are not willing to settle that claim.
“There are a lot of provisions within NIIRA to ensure that insurance companies do so when they are required.
“In addition, there is also self-regulation, ensuring that we look for reasons to settle a claim and not reasons not to settle a claim.
“It’s not really about awareness that people are not taking up insurance. Fundamentally, it comes down to claims. So, capital is good, but how we utilise that capital to bring more people under insurance coverage will be fundamentally driven by how well we pay our claims and how efficiently we do so.”
The market is likely to become more concentrated, with six licenses cancelled by the commission. That could make insurers more financially resilient, but the industry must make sure it does not reduce competition or limit policyholders choices.
Insurers also face tougher shareholder expectations, which could push them to price and select risks more carefully.
Risk-Based Capital framework, which will tie the capital an insurer must hold to the risks it actually takes on. Meeting the minimum is no longer the issue.
In conclusion, operators now have the capital but will policyholders see the difference?
- #Claims Settlement
- Aiico insurance
- Babatunde Fajemirokun
- consumer protection
- insurance claims
- insurance licences
- insurance recapitalisation
- Minimum Capital Requirement
- NAICOM
- Nia
- Nigerian insurance industry
- Nigerian Insurance Industry Reform Act
- NIIRA 2025
- Policyholders
- Post Recapitalisation: What changes when you make a claim?
- Post-Recapitalisation
- Risk-Based Capital
- Underwriting Capacity